Five equity-backed notes issued through Luxembourg’s ORO II fund will trade against dollars, USDT and Bitcoin for eligible non-US investors.
 Live Chat

Five equity-backed notes issued through Luxembourg’s ORO II fund will trade against dollars, USDT and Bitcoin for eligible non-US investors.
Cointelegraph is committed to providing independent, high-quality journalism across the crypto, blockchain, AI, and fintech industries.
All news, reviews, and analyses are produced with full journalistic independence and integrity. For more details on our standards and processes, please read our Editorial Policy.
Blockchain data reviewed by CoinDesk shows wallets tied to North Korea’s Lazarus Group sold more than $30 million in bitcoin on the platform in the last three weeks alone.
Mutsamudu, Comoros, August 31, 2026 – MEXC, a pioneer in 0-fee digital asset trading, reports a sharp rise in Spot trading activity on the platform as BTC topped $80,000 and ETH and SOL reached near six-month highs. From August 20 to 22, the average daily Spot trading volume of BTC, ETH, SOL, and XRP increased by approximately 299% from the daily average recorded between August 1 and 17. Over the same period, the combined average daily trading volume of ETH, SOL, and XRP exceeded that of BTC. Compared with the BTC-dominated trading structure seen from August 1 to 17, activity on the platform spread noticeably across a broader range of major assets.
This shift in trading composition had already emerged on August 19. On that day, the combined trading share of ETH, SOL, and XRP rose from 30.5% a day earlier to 46.7%, an increase of 16.2 percentage points and the largest single-day gain in August. Their combined daily share subsequently remained above the 34.9% baseline recorded from August 1 to 17, indicating that trading interest in these three major assets had begun to rise before BTC broke above $80,000.
On August 25, when BTC topped $80,000, BTC Spot trading volume increased by approximately 164% from the August 1 to 17 daily average. ETH volume rose by 220%, while SOL and XRP each increased by approximately 500%. BTC remained an important market signal during this rally, but the increase in platform activity was not limited to BTC. Instead, multiple major assets became active at the same time.
The trend continued on August 27, when ETH and SOL climbed to nearly six-month highs. On MEXC, ETH Spot trading volume increased by 36.3% from the previous day, while SOL volume rose by 109.7%. Together, the two assets accounted for 46.4% of combined trading volume across the four assets, marking a new August high and making them the primary drivers of the day’s increase in trading activity.
As market sentiment strengthens, trading demand can rotate quickly across major assets, making trading costs and execution efficiency increasingly important for users seeking to respond to market movements. MEXC currently offers 0-fee trading on selected SOL Spot trading pairs and all XRP Spot trading pairs. Combined with deep liquidity, this enables users to navigate market rotations at lower cost and with greater efficiency while capturing more opportunities.
About MEXC
MEXC is the world’s fastest-growing cryptocurrency exchange, trusted by more than 40 million users across 170+ markets. Built on a user-first philosophy, MEXC offers industry-leading 0-fee trading and access to over 3,000 digital assets. As the Gateway to Infinite Opportunities, MEXC provides a single platform where users can easily trade cryptocurrencies alongside tokenized assets, including stocks, ETFs, commodities, and precious metals.
MEXC Official Website| X | Telegram |How to Sign Up on MEXC
For media inquiries, please contact MEXC PR team: media@mexc.com
Bitmine owns 4.9% of the total ETH coin supply of 120.7 million
Bitmine is 98% of the way to the ‘Alchemy of 5%’ in just 15 months
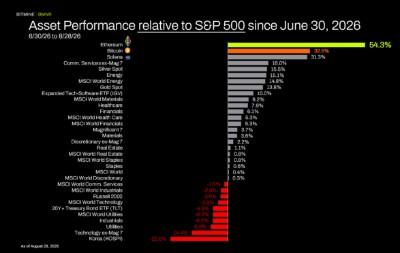
ETH is the best performing macro asset in 3Q26 so far, outperforming the S&P 500 by 5,430bp
Bitmine was added to the Russell 1000 Large-cap index on June 26, 2026
Bitmine’s Series A Preferred Stock is trading on the NYSE under the symbol BMNP
Bitmine has 5,067,309 staked ETH, representing $12.7 billion at $2,511 per ETH. MAVAN (Made in America VAlidator Network) is a premier Ethereum staking destination for BMNR and institutional investors
Bitmine owns $81 million of Eightco (NASDAQ: ORBS), now one of the only publicly listed equities in the world to provide investors indirect exposure to OpenAI
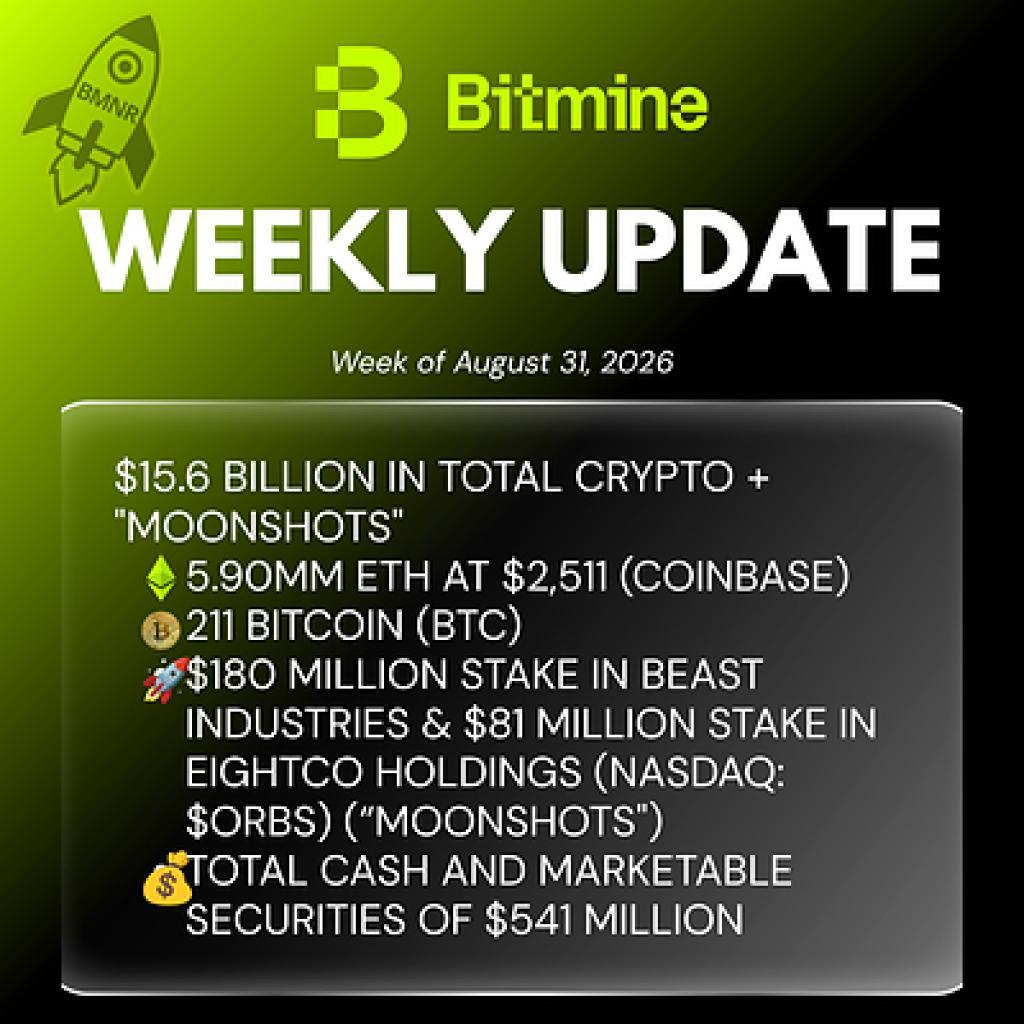
Bitmine Crypto + Total Cash Holdings & Marketable Securities + “Moonshots” total $15.6 billion, including 5.90 million ETH tokens, total cash & marketable securities of $541 million, and other crypto holdings
Bitmine remains supported by a premier group of institutional investors including ARK’s Cathie Wood, MOZAYYX, Founders Fund, Bill Miller III, Pantera, Kraken, DCG, Galaxy Digital and personal investor Thomas “Tom” Lee to support Bitmine’s goal of acquiring 5% of ETH
NORWALK, Conn., Aug. 31, 2026 /PRNewswire/ — (NYSE: BMNR) Bitmine Immersion Technologies, Inc. (“Bitmine” or the “Company”) a Bitcoin and Ethereum Network company with a focus on the accumulation of crypto for long term investment, today announced Bitmine crypto + total cash & marketable securities + “moonshots” holdings totaling $15.6 billion.
As of August 30, 2026 at 3:00pm ET, the Company’s crypto holdings are comprised of 5,901,112 ETH at $2,511 per ETH (per Coinbase NASDAQ: COIN), 211 Bitcoin (BTC), $180 million stake in Beast Industries, $81 million stake in Eightco Holdings (NASDAQ: ORBS) (“moonshots”) and total cash & marketable securities of $541 million. Bitmine’s ETH holdings are 4.9% of the ETH supply (of 120.7 million ETH).
“As we enter the final month of 3Q26, ETH is the best performing macro asset, outperforming the S&P 500 by 5,430bp through last Friday. In fact, the top 3 performing assets since June 30th are ETH, BTC and SOL,” stated Thomas “Tom” Lee, Chairman of Bitmine. “We believe this sets the stage for institutions to add to their crypto holdings given the substantial outperformance of crypto versus other macro assets in 3Q so far.”
“We believe there are multiple positive catalysts as we head into the final months of 2026,” stated Lee. “These include the upcoming CLARITY Act vote scheduled in mid-Sept. Additionally, Korean investors have again started buying crypto and rotating away from AI stocks. The 4-year cycle is bottoming within the next few weeks in our view. And this sets the stage for what we expect to be sizable institutional participation in buying crypto in the final months of 2026, especially given the tailwinds of tokenization and Agentic-AI.”
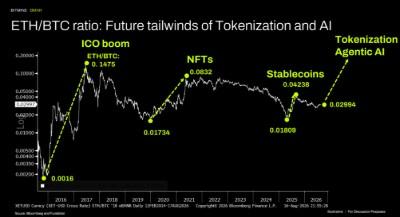
“This ETH/BTC ratio has moved up during crypto bull cycles, driven by increasing use of Ethereum relative to bitcoin. These prior cycles were fueled by ICOs (2017-2018), NFTs (2020-2021), and stablecoins (2025). In this upcoming crypto cycle, we see the ETH/BTC ratio rising, driven by Wall Street tokenizing on the blockchain and by agentic-AI using blockchains,” continued Lee.
“Over the past week, we acquired 53,501 ETH. Bitmine has bought ETH for each of the past 65 weeks (every week since the inception of the ETH Treasury Strategy on June 30, 2025),” stated Lee.
On July 16, 2026, Bitmine released the latest Chairman’s Message (link here) for July 2026. The title of the Message is “ETH is the cure for the Uncanny Valley of Wealth.”
Earlier in 2026, Bitmine launched MAVAN (the Made in America VAlidator Network), the institutional-grade staking platform. While MAVAN was originally developed to support Bitmine’s own Ethereum treasury, MAVAN intends to expand to serve institutional investors, custodians, and ecosystem partners seeking best-in-class staking infrastructure. A portion of Bitmine’s ETH is already staked on the MAVAN platform.
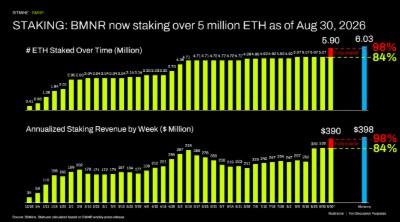
As of August 30, 2026, Bitmine total staked ETH stands at 5,067,309 ($12.7 billion at $2,511 per ETH). “Bitmine has staked more ETH than other entities in the world. At scale (when Bitmine’s ETH is fully staked by MAVAN and its staking partners), the projected ETH staking reward is $390 million on an annualized basis (using 2.63% 7-day BMNR yield),” stated Lee.
“Annualized staking revenues are now projected at $335 million. And this 5.1 million ETH is 86% of the 5.90 million ETH held by Bitmine. Bitmine’s own staking operations generated a 7-day yield of 2.63% (annualized),” continued Lee.
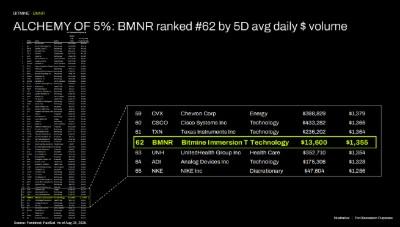
Bitmine is one of the most widely traded stocks in the US. According to data from Fundstrat, the stock has traded average daily dollar volume of $1.36 billion (5-day average, as of August 29, 2026), ranking #62 in the US, behind Texas Instruments (rank #61) and ahead of UnitedHealth Group (rank #63) among 5,704 US-listed stocks (statista.com and Fundstrat research).
Bitmine’s crypto holdings reign as the #1 Ethereum treasury and #2 global treasury, behind Strategy Inc. (NASDAQ: MSTR), which reportedly owns 840,447 BTC valued at approximately $66 billion. Bitmine remains the largest ETH treasury in the world.
Bitmine management believes the GENIUS Act and the Securities and Exchange Commission’s (SEC) Project Crypto are as transformational to financial services in 2026 as the US action on August 15, 1971, which ended the Bretton Woods system and took the U.S. dollar off the gold standard 55 years ago. This 1971 event was the catalyst for the modernization of Wall Street, creating the iconic Wall Street titans and financial and payment rails of today. These proved to be better investments than gold.
The Chairman’s message can be found here:
https://www.Bitminetech.io/chairmans-message
The Fiscal Full Year 2025 Earnings presentation and corporate presentation can be found here: https://Bitminetech.io/investor-relations/
To stay informed, please sign up at: https://Bitminetech.io/contact-us/
About Bitmine
Bitmine Immersion Technologies, Inc. (NYSE: BMNR), together with its subsidiaries (“Bitmine” or the “Company”), is a blockchain technology infrastructure company operating across institutional digital asset staking and validation services, bitcoin mining, and strategic digital asset management. As the world’s leading Ethereum Treasury company, it implements an innovative digital asset strategy for institutional investors and public market participants. The Company provides institutional-grade staking and validation infrastructure—through which it earns staking rewards and validation income—alongside bitcoin mining activities. Bitmine holds digital assets strategically, generating yield on those holdings to support liquidity and capital formation. Since 2025, the Company has expanded its blockchain infrastructure capabilities, including developing and deploying MAVAN, its institutional staking and validation platform. The Company’s activities further include investments in early-stage blockchain opportunities (“moonshot” investments) and ancillary mining, hosting, and consulting services.
For additional details, follow on X:
Forward Looking Statements
This press release contains statements that constitute “forward-looking statements” within the meaning of the Private Securities Litigation Reform Act of 1995, as amended. Forward-looking statements include all statements that are not purely historical and can generally be identified by terms such as “expects,” “projects,” “intends,” “plans,” “believes,” “anticipates,” “estimates,” “forecasts,” “targets,” “goals,” “may,” “will,” “would,” “could,” “should,” “view,” “see,” or similar expressions, or the negative of such terms, or other comparable terminology. This press release specifically contains forward-looking statements regarding, among other things: (i) the Company’s goal of acquiring 5% of the total ETH supply (the “Alchemy of 5%” initiative) and statements regarding its progress toward this goal; (ii) the Company’s digital asset accumulation and treasury strategy, including statements regarding continued weekly ETH acquisitions and the Company’s status as the largest ETH treasury in the world; (iii) the Company’s staking operations, including projected annualized ETH staking rewards of approximately $396 million at scale (assuming Bitmine’s ETH is fully staked by MAVAN and its staking partners), currently projected annualized staking revenues of approximately $340 million, and the 7-day yield of 2.67% (annualized); (iv) MAVAN’s intended expansion to serve institutional investors, custodians, and ecosystem partners seeking best-in-class staking infrastructure, and its intended position as a premier Ethereum staking destination for BMNR and institutional investors; (v) expectations regarding future ETH and other digital asset price performance, including statements regarding ETH’s performance relative to the S&P 500 and other macro assets in 3Q26 and the expectation that institutions will add to their crypto holdings; (vi) management’s belief that multiple positive catalysts exist heading into the final months of 2026, including the CLARITY Act vote scheduled for mid-September 2026, renewed buying by Korean investors and rotation away from AI stocks, the view that the four-year crypto cycle is bottoming within the next few weeks, and the expectation of sizable institutional participation in buying crypto in the final months of 2026, including the anticipated tailwinds of tokenization and agentic-AI; (vii) statements and expectations regarding the ETH/BTC ratio, including that the ratio will rise in the upcoming crypto cycle driven by Wall Street tokenizing on the blockchain and by agentic-AI using blockchains; (viii) management’s belief that the GENIUS Act and SEC Project Crypto are “as transformational to financial services” as the end of the Bretton Woods system in 1971, and that the resulting investments will prove better than gold; (ix) statements regarding the Company’s investment in Eightco Holdings (NASDAQ: ORBS) as providing indirect exposure to OpenAI, and its investment in Beast Industries; (x) statements regarding the value of the Company’s crypto, cash, marketable securities, and “moonshot” holdings, including aggregate holdings of $15.6 billion and ETH holdings representing 4.9% of the total ETH supply; and (xi) the future growth, advancement, and strategic direction of the Company’s Ethereum treasury strategy, blockchain infrastructure capabilities, bitcoin mining operations, and MAVAN staking platform.
These forward-looking statements involve substantial risks and uncertainties that could cause actual results to differ materially from those expressed or implied. Factors that could cause or contribute to such differences include, but are not limited to: the extreme volatility and unpredictability of digital asset prices, including ETH and Bitcoin, and the speculative nature of digital asset investments; the risk that historical ETH price movements and relative performance versus other macro assets will not recur or are not indicative of future performance; the Company’s reliance on third-party pricing sources and reported market values in calculating the value of its crypto, cash, marketable securities, and “moonshot” holdings, and the risk that such values fluctuate materially after the date and time referenced in this release; changes in market conditions affecting the trading price and trading volume of the Company’s common stock and Series A Preferred Stock, and the risk that the Company’s inclusion in the Russell 1000 index does not produce anticipated benefits; the Company’s ability to successfully execute its digital asset acquisition strategy and achieve its ETH accumulation targets, including the “Alchemy of 5%” goal; the Company’s ability to finance its business operations, Ethereum treasury operations, and MAVAN expansion; operational, security, and technological risks associated with the Company’s staking and validation operations, including network failures, slashing events, cybersecurity breaches, and protocol changes; the risk that actual staking participation, yields, rewards, and revenues differ materially from the projected amounts described in this release, which are based on a 7-day yield and assume ETH is fully staked at scale; competition in the digital asset treasury, staking, and mining industries; the Company’s dependence on key personnel, including executive leadership; regulatory developments affecting digital assets, blockchain technology, and staking activities in the United States and globally, including the timing and outcome of the scheduled CLARITY Act vote and the ultimate enactment, implementation, and interpretation of the GENIUS Act and other pending legislation and regulatory initiatives; actions by the SEC, CFTC, and other regulatory bodies affecting digital assets and related businesses; risks related to the Company’s investments in early-stage blockchain opportunities (“moonshot” investments), including the investments in Eightco Holdings and Beast Industries and any indirect exposure to OpenAI; macroeconomic factors, including inflation, interest rates, Federal Reserve monetary policy, labor market conditions, investor flows in international markets, and general economic conditions affecting investor sentiment toward digital assets; the accuracy of management’s expectations regarding the ETH/BTC ratio and the impact of tokenization and agentic-AI applications on Ethereum; the unpredictability of cryptocurrency market cycles and the accuracy of expectations regarding future crypto cycles, including whether the four-year cycle bottoms as anticipated and whether institutional participation materializes; changes to the Ethereum protocol, including staking mechanics, validator requirements, and reward structures; risks related to AI systems and their potential impact on cryptocurrency markets and blockchain technology; the performance of third-party service providers, exchanges, custodians, and staking partners; risks related to the concentration of the Company’s assets in digital currencies, particularly Ethereum; and the other risk factors described in the Company’s filings with the SEC.
The forward-looking statements contained in this press release are based on information available to management as of the date of this release and reflect management’s current expectations, estimates, forecasts, projections, views, and beliefs concerning future events and circumstances. Actual results may vary materially from those expressed or implied by forward-looking statements based on a number of factors, including those described above and in the Risk Factors section of the Company’s Annual Report on Form 10-K for the fiscal year ended September 30, 2025 filed with the SEC on November 21, 2025, the Company’s Quarterly Reports on Form 10-Q, and the Company’s other filings with the SEC, as amended or updated from time to time. Copies of these filings are available on the SEC’s website at www.sec.gov and on the Company’s website at https://Bitminetech.io/investor-relations/. The Company cautions readers not to place undue reliance on any forward-looking statements, which speak only as of the date on which they are made. Bitmine expressly disclaims any obligation or undertaking to update, revise, or supplement any forward-looking statements to reflect any change in its expectations or any change in events, conditions, or circumstances on which any such statements are based, except as required by applicable law or regulation.
Start every day with the top news stories right now, plus original features, a podcast, videos and more.
Mutsamudu, Comoros, August 31st, 2026, Chainwire
MEXC, a pioneer in 0-fee digital asset trading, reports a sharp rise in Spot trading activity on the platform as BTC topped $80,000 and ETH and SOL reached near six-month highs. From August 20 to 22, the average daily Spot trading volume of BTC, ETH, SOL, and XRP increased by approximately 299% from the daily average recorded between August 1 and 17. Over the same period, the combined average daily trading volume of ETH, SOL, and XRP exceeded that of BTC. Compared with the BTC-dominated trading structure seen from August 1 to 17, activity on the platform spread noticeably across a broader range of major assets.
This shift in trading composition had already emerged on August 19. On that day, the combined trading share of ETH, SOL, and XRP rose from 30.5% a day earlier to 46.7%, an increase of 16.2 percentage points and the largest single-day gain in August. Their combined daily share subsequently remained above the 34.9% baseline recorded from August 1 to 17, indicating that trading interest in these three major assets had begun to rise before BTC broke above $80,000.
On August 25, when BTC topped $80,000, BTC Spot trading volume increased by approximately 164% from the August 1 to 17 daily average. ETH volume rose by 220%, while SOL and XRP each increased by approximately 500%. BTC remained an important market signal during this rally, but the increase in platform activity was not limited to BTC. Instead, multiple major assets became active at the same time.
The trend continued on August 27, when ETH and SOL climbed to nearly six-month highs. On MEXC, ETH Spot trading volume increased by 36.3% from the previous day, while SOL volume rose by 109.7%. Together, the two assets accounted for 46.4% of combined trading volume across the four assets, marking a new August high and making them the primary drivers of the day’s increase in trading activity.
As market sentiment strengthens, trading demand can rotate quickly across major assets, making trading costs and execution efficiency increasingly important for users seeking to respond to market movements. MEXC currently offers 0-fee trading on selected SOL Spot trading pairs and all XRP Spot trading pairs. Combined with deep liquidity, this enables users to navigate market rotations at lower cost and with greater efficiency while capturing more opportunities.
About MEXC
MEXC is the world’s fastest-growing cryptocurrency exchange, trusted by more than 40 million users across 170+ markets. Built on a user-first philosophy, MEXC offers industry-leading 0-fee trading and access to over 3,000 digital assets. As the Gateway to Infinite Opportunities, MEXC provides a single platform where users can easily trade cryptocurrencies alongside tokenized assets, including stocks, ETFs, commodities, and precious metals.
MEXC Official Website| X | Telegram |How to Sign Up on MEXC
For media inquiries, please contact MEXC PR team: media@mexc.com
MEXC PR team
media@mexc.com
The Ninth Circuit has dealt Kalshi one of its biggest legal losses yet, ruling that the platform’s sports-event contracts are sports bets—not swaps protected by the Commodity Exchange Act. The decision lets Nevada enforce its gaming laws against Kalshi’s sports products, deepens a circuit split with the Third Circuit, and raises the stakes for prediction-market operators facing state regulators around the country.
The United States Court of Appeals for the Ninth Circuit delivered a major win to Nevada Friday, and a major setback to Kalshi’s central legal argument for offering sports contracts nationwide.
In a published opinion, a unanimous three-judge panel affirmed the dissolution of Kalshi’s preliminary injunction against Nevada gaming regulators. The court held that Kalshi had not shown it was likely to prove that the Commodity Exchange Act preempts Nevada’s gambling laws as applied to its sports-event contracts.
The key conclusion was blunt: Kalshi’s sports products are sports bets, not Commodity Futures Trading Commission-regulated swaps.
That does not end Kalshi’s case altogether. The court remanded the dispute over Kalshi’s election contracts to the Nevada district court for separate consideration. But for the platform’s sports business, the part that made up more than 90% of Kalshi trades and 95% of its revenue in 2025, according to the opinion, the ruling is a serious legal problem.
The dispute began in March 2025, when the Nevada Gaming Control Board sent Kalshi a cease-and-desist letter. Nevada argued that the company’s sports-event contracts constituted an unlicensed sports pool under state gaming law.
Kalshi argued that it is not a sportsbook but a CFTC-registered designated contract market (DCM) listing federally regulated event contracts. It stated the CFTC’s authority over swaps preempted Nevada’s gaming rules. A district judge initially gave Kalshi a preliminary injunction, but later dissolved it after a separate Nevada ruling against Crypto.com reached the opposite conclusion on similar sports contracts.
Friday’s appeals decision backs Nevada’s position. The court held that the Commodity Exchange Act gives the CFTC exclusive jurisdiction over qualifying swaps traded on a DCM, but that Kalshi’s contracts on sports outcomes do not qualify as swaps in the first place.
The panel said a bet on whether a team covers a spread, wins a game, or hits a particular score is not materially different from the same wager at a conventional sportsbook. Kalshi’s market structure may differ from Caesars or MGM, the court said, but those differences do not change the legal substance of the product.
Kalshi’s argument centered on the broad statutory definition of a swap: a contract tied to the occurrence or nonoccurrence of an event or contingency that carries a potential financial, economic or commercial consequence.
The Ninth Circuit agreed that the CEA can preempt some state regulation of swaps traded on federally designated markets. But it rejected Kalshi’s view that every event contract listed on a DCM automatically receives that federal shield.
The court’s reasoning had three major pieces:
The judges also rejected Kalshi’s claims of conflict and field preemption. They said Kalshi could comply with Nevada law by geofencing users in Nevada, as other regulated entities do. They held that Congress had not clearly given the CFTC authority to displace states’ longstanding role in regulating gambling.
The ruling creates a direct and increasingly consequential split with the Third Circuit.
Earlier this year, the Third Circuit affirmed an injunction protecting Kalshi from New Jersey gambling enforcement, concluding that Kalshi’s sports-related event contracts could be treated as swaps under the CEA and that federal law preempted the state’s attempt to regulate them.
The Ninth Circuit explicitly disagreed with that approach. It said the Third Circuit read the term “event” too literally and failed to account for the statutory context, the CFTC’s prohibition on gaming, and the fact that Congress has historically treated sports gambling as an area for state and tribal regulation.
That leaves two federal appellate courts interpreting the same federal law differently. Kalshi may seek rehearing or Supreme Court review, particularly because the CFTC appeared as an amicus supporting the company’s position. But for now, the Ninth Circuit’s decision is controlling across a large portion of the West.
The American Gaming Association hailed the decision as a victory for state authority and the established gaming framework.
“The Ninth Circuit’s unanimous decision confirmed state and voter choices about sports betting in their communities,” the AGA said in a statement. “The American Gaming Association applauds Nevada’s leadership for protecting and preserving the state- and tribal-regulated gaming framework. This ruling is a significant win for consumer protections and taxpayers.
“It is a big loss for Kalshi and other backdoor sports gambling operations who defy state laws.”
The Nevada ruling is a major setback for prediction markets, but it does not settle the nationwide fight.
Kalshi has picked up preliminary-injunction wins in New Jersey, Tennessee and Arizona, while courts in Maryland, Ohio, New York and now Nevada have rejected or limited its preemption argument. The Fourth Circuit appeal from the Maryland decision is still pending, and the Ninth Circuit’s ruling notes that litigation remains active in multiple jurisdictions.
The immediate practical distinction is between sports contracts and other types of event contracts. The Ninth Circuit sent the question of Kalshi’s election markets back to the Nevada district court rather than deciding it, leaving political prediction markets outside the court’s core holding for now.
Solana validators just made a big call. They’ve collectively agreed to cancel 18.9 million SOL in a direct effort to pull back on inflation that’s been eating at the network’s economic stability.
That’s not a small number. Burning nearly 19 million SOL is a hard, deliberate move — the kind that doesn’t happen without serious internal pressure from stakeholders who’ve watched inflationary dynamics quietly erode confidence in the ecosystem. Validators didn’t drift into this decision. They pushed for it, agreed on it, and moved. The goal is pretty much what you’d expect: tighten supply, stabilize the network, and send a signal to investors and users that the people running Solana’s infrastructure are paying attention to the economics. Crypto networks live and die by that kind of confidence, and Solana’s validators seem to know it. Whether it’s enough to shift sentiment in any lasting way is unclear — no detailed public roadmap followed the announcement, and key stakeholders haven’t offered much beyond the basic facts of the cancellation itself.
No further comment. No timeline.
Inflation has been a real friction point for Solana for a while now. The network’s staking rewards and issuance model have generated ongoing debate about whether SOL’s supply growth was outpacing the kind of organic demand needed to keep the token’s value from drifting. Canceling 18.9 million SOL doesn’t fix everything — it’s probably not meant to. But it does reduce the circulating pressure and creates a more balanced supply environment, at least on paper. Validators are basically saying they’d rather absorb the short-term procedural cost of a cancellation than let inflation keep running unchecked.
It’s a proactive call. And it’s the kind of move that tends to matter more over months than over days.
The broader crypto market has seen similar debates play out across other networks — supply management, burn mechanisms, and validator governance have become increasingly central to how blockchain ecosystems try to maintain economic credibility. Solana’s decision fits into that pattern, even if the specifics are its own.
Separately, Bitcoin is moving toward quantum-resistant defenses. The threat from quantum computing isn’t immediate — most experts put truly dangerous quantum capability years out — but Bitcoin’s development community isn’t waiting. The push to integrate quantum-resistant cryptographic measures is about future-proofing infrastructure before the problem arrives, not scrambling after it does.
That’s a meaningful distinction. Traditional cryptographic methods that secure Bitcoin transactions could, in theory, become vulnerable as quantum computing scales. The math behind current encryption wasn’t built with quantum processors in mind. Bitcoin’s initiative to address that gap early is a calculated bet that the cost of acting now is far lower than the cost of reacting later.
No specific implementation date was given. Unclear how far along the technical work actually is. But the direction is set.
And it matters for trust. Bitcoin’s value proposition has always rested heavily on security — the idea that the network is essentially unbreakable under current conditions. Extending that promise into a quantum-computing future requires real engineering work, and the fact that it’s being prioritized says something about where Bitcoin’s development focus sits right now.
Meanwhile, financial firm Bernstein put out a bullish projection: Bitcoin could hit $500,000 within this market cycle. That’s a striking number. Bernstein tied the outlook to both technological progress and what it sees as favorable market positioning for Bitcoin over the longer term.
$500,000 would represent a massive move from where Bitcoin has traded. Bernstein didn’t break down the exact mechanics of how it gets there — at least not in what’s been made public — but the projection fits a broader pattern of institutional analysts taking increasingly aggressive long-term stances on Bitcoin’s ceiling. Whether that confidence is warranted depends on factors that are still pretty murky: regulatory clarity, macro conditions, adoption curves, and yes, how well Bitcoin’s infrastructure holds up as threats like quantum computing evolve.
Bernstein’s call is optimistic. Maybe aggressively so. But it’s not coming from nowhere — it’s grounded in the firm’s read on where Bitcoin’s fundamentals and strategic positioning are headed.
For now, the 18.9 million SOL cancellation stands as Solana’s most concrete recent move, and Bernstein’s $500,000 Bitcoin target sits as the most specific number anyone’s attached to crypto’s near-term ceiling.
Hub: Bitcoin price, news, and analysis
Solana validators agreed to cancel 18.9 million SOL as a direct measure to reduce inflationary pressure and stabilize the network’s economic environment.
Financial firm Bernstein projected that Bitcoin could reach a peak value of $500,000 within the current market cycle, citing technological advancements and market positioning.
The decision to burn 18.9 million SOL underscores the growing urgency among Solana validators to address inflationary concerns that could undermine investor confidence and the network’s long-term viability. This move reflects a broader trend within the crypto space, where projects are increasingly focusing on economic sustainability and governance responsiveness to maintain their competitive edge. As Solana implements such significant measures, it could influence market perceptions and set a precedent for other networks grappling with similar inflationary pressures.
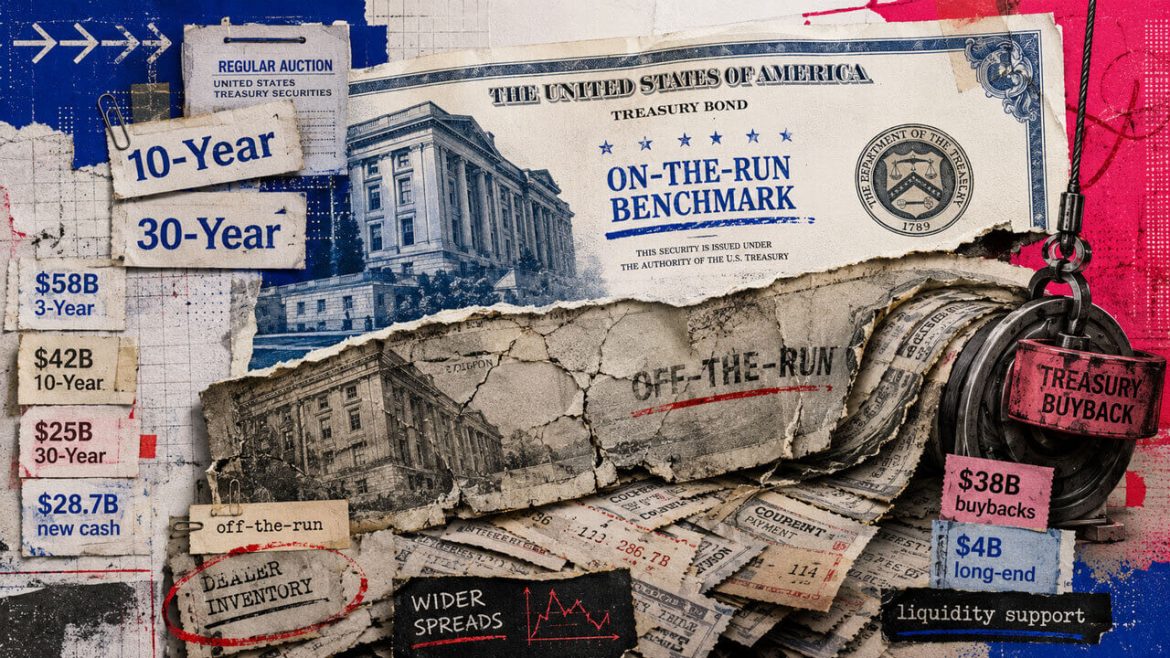
The US Treasury expects to borrow $739 billion from July through September while paying investors to hand back some of its older bonds. The pairing looks self-defeating because both transactions involve the same issuer. However, they are on separate ledgers and solve separate problems: auctions finance the government and create liquid benchmarks, while buybacks retire selected old issues or help Treasury manage its cash balance.
Treasury’s Aug. 3 borrowing estimate assumes a $950 billion cash balance at the end of September, then projects another $628 billion of borrowing from October through December. Its August refunding statement authorized as much as $38 billion of liquidity-support purchases and $25 billion of short-dated cash-management purchases during the current quarter.
Treasury widened the program on Aug. 19, lifting the maximum size of each buyback in the 10-to-20-year and 20-to-30-year sectors from $2 billion to at least $4 billion for operations from Sept. 9 through Nov. 4.
The announcement kept the regular auction schedule intact and confirmed that purchased debt will generally be replaced through new issuance, giving the government room to sell and buy bonds during the same financing cycle. Because the expansion came later, the earlier $38 billion quarterly figure isn’t a final ceiling for long-end purchases.
Treasury sells bills, notes, bonds, floating-rate notes, and inflation-protected securities to fund the gap between federal receipts and spending, refinance maturing debt, and maintain its cash balance. Bills mature within a year and are generally sold at a discount, while notes and bonds usually pay interest every six months across maturities from two to 30 years. “Coupon” is the old name for that periodic interest payment, inherited from the paper certificates whose interest slips investors once clipped by hand.
An auction can introduce a new security or reopen an existing one, with competitive bids establishing the market-clearing yield and price. A new 10-year note receives a fresh CUSIP and becomes the current benchmark, while a reopening adds supply to that same security at a later auction. The August refunding, for example, comprised a $58 billion three-year note, a $42 billion 10-year note and a $25 billion 30-year bond, producing $28.7 billion of new cash once maturing securities were accounted for.
The newest security in a maturity bucket becomes the on-the-run issue, usually trading more frequently and at tighter bid-ask spreads than comparable older bonds. Traders and institutions use it for hedging and price discovery, giving Treasury a reason to keep benchmark auctions large and predictable even when its cash balance can support buybacks.
Once a new security replaces it, the previous benchmark becomes off-the-run while retaining the same federal guarantee and scheduled payments. Trading migrates toward the fresh issue and the pool of natural buyers narrows, leaving dealers to use more balance-sheet capacity when they warehouse the older bond. Investors can then face a wider selling spread, and small price gaps can open between securities with nearly identical interest-rate exposure.
Across a debt market measured in tens of trillions of dollars, small trading frictions become expensive when volatility consumes dealer capacity, and investors crowd into the newest issues. An old Treasury can retain the same credit quality and cash flows while becoming inconvenient to sell, which is why a liquidity-support buyback gives dealers and other holders a regular outlet for selected off-the-run supply.
Treasury announces an eligible maturity bucket and a maximum purchase amount before each operation, then approved counterparties submit competitive offers through FedTrade, with the New York Fed acting as Treasury’s fiscal agent. Sellers specify the security and price, and Treasury evaluates those offers using market prices and relative value across eligible issues, according to its buyback guidance.
It can accept less than the published maximum when prices look unattractive, preserving the discipline of an auction rather than guaranteeing every seller an exit.
Liquidity-support operations focus on older coupons whose trading can benefit from a regular buyer, with Treasury retiring accepted securities as scheduled auctions keep building the current benchmarks. Josh Frost, then Treasury’s assistant secretary for financial markets, described the program as a tool for ordinary market functioning that can reduce fragmented supply and free dealer capacity between operations.
Cash-management buybacks address a different problem because tax receipts, spending, maturities, and auction settlements arrive in uneven waves.
Treasury can buy securities that are close to maturity when its cash balance would otherwise run higher than desired, smoothing upcoming redemptions and giving debt managers more control over near-term cash needs. That flexibility also reduces the need for abrupt bill-auction adjustments around large payment dates.
Treasury’s own borrowing estimates exclude a large net effect from the program because every repurchased dollar has to be financed somewhere else, all else equal. If Treasury sells $100 billion of new securities to private investors and buys back $4 billion held by private investors, privately held debt has increased by $96 billion. Reaching a $100 billion net borrowing target alongside that purchase would require roughly $104 billion of gross issuance.
That also lets sales and purchases expand together because the Treasury can deepen a current benchmark, remove a slice of older supply and still raise the net cash in its financing plan. The federal deficit determines the net financing need, while buybacks alter the age, composition, and maturity profile of debt held by the public.
Auction proceeds and buyback payments pass through the Treasury General Account, the federal government’s operating account at the Fed. When private buyers settle a Treasury auction, money moves toward the TGA and reserve balances in the banking system generally decline, all else equal. Federal spending and Treasury buybacks send funds back toward private accounts, generally adding reserves along the way.
The Fed’s Aug. 27 H.4.1 release showed the TGA averaging $950.7 billion during the week ended Aug. 26 and standing at $959.4 billion on Wednesday, while reserve balances averaged $2.92 trillion. Treasury expects the account to finish September near $950 billion, reach roughly $1.05 trillion, plus or minus $50 billion, in late October and settle near $850 billion at year-end.
A $4 billion buyback can therefore put cash into sellers’ hands on settlement day, and a larger auction can pull cash toward the TGA on another day. Taxes and federal outlays add more movements, so the reserve path depends on the full calendar rather than the headline maximum attached to one operation. Timing can loosen or tighten dollar availability for several days even when the quarter’s net borrowing estimate barely moves.
The source of the money separates Treasury buybacks from quantitative easing because the Fed creates reserve balances when it purchases securities for its own portfolio, adding reserves to its liabilities and bonds to its assets. Treasury spends an existing TGA balance and replenishes that balance through taxes or debt sales, while repurchased securities are retired instead of joining a monetary-policy portfolio.
Those balance sheets give the two programs different effects because removing off-the-run duration can free dealer capacity, narrow relative-value gaps, and make long bonds easier to transact, while surrounding Treasury issuance can absorb cash and add duration elsewhere. Accepted offers, auction demand, settlement dates and maturity buckets determine the combined result.
Treasury preserves that two-sided structure because shrinking benchmark auctions whenever cash-management needs fluctuate would make issuance less predictable, fragment current securities, and risk higher financing costs over time. Regular auctions give investors dependable supply, while selective purchases let debt managers address older pockets of inventory without rebuilding the entire calendar around temporary cash swings.
Long-dated bonds are the most price-sensitive securities in the regular auction schedule, and warehousing them consumes more dealer risk capacity when yields move sharply. Older 20- and 30-year issues can linger once demand concentrates in a fresh benchmark, so doubling the per-operation ceiling gives Treasury more room to buy attractive offers while retaining the option to stop below the cap.
Treasury’s formal objective is ordinary market functioning, and the agency hasn’t announced a target for long-term yields. Purchases can still affect relative prices at the margin because they remove duration from selected issues and give dealers another buyer, which makes intent and market effect separate parts of the analysis. A $4 billion operation can ease a local pocket of illiquidity, while its scale stays small beside a Treasury market measured in tens of trillions of dollars.
For Bitcoin, the connection runs through reserve availability, long-term yields, collateral markets, and dealer capacity, all of which influence the cost of carrying risk across asset classes. CryptoSlate has tracked how Treasury yields can transmit stress into Bitcoin, and buybacks enter that channel by easing selected bond inventories while auctions move cash toward the TGA.
A well-received long-bond buyback could ease a local dislocation and lower one source of cross-market strain, while a heavy auction week or a rapid TGA build could absorb cash at the same time. Bitcoin can benefit when yields settle and dollar availability improves, though the size and timing of those effects have to be measured across the whole financing schedule. Treating every purchase ceiling as an equal injection assigns the program a power its funding mechanics don’t provide.
The larger long-end operations begin Sept. 9, and the next quarterly refunding announcement arrives Nov. 4. Accepted purchase amounts, offered prices, demand for the new benchmarks, and the TGA path around settlement will show how much Treasury has improved trading in old bonds while continuing to finance the government through new ones.


